Blog
How to run a Business Credit Check before offering payment terms
Understand customer risk more clearly before extending credit and putting cash flow on the line
6 October 2026
read
Summary
- Business credit checks can help you assess customer risk before agreeing payment terms.
- Key areas to review include company identity, credit score, payment behaviour, CCJs, insolvency indicators and filings.
- The results can help you decide whether to offer standard terms, reduce credit limits, request upfront payment or decline credit.
- Using credit insight can support more consistent decisions and help protect cash flow.
Offering payment terms can help you win customers, build loyalty and support larger orders. It also creates exposure. Once goods or services have been delivered, your business is carrying the risk until the invoice is paid.
For SMEs, that risk can affect cash flow quickly. A late or unpaid invoice may limit your ability to pay suppliers, fund payroll, invest in stock or take on the next opportunity.
A business credit check helps you assess that risk before you agree to 30, 60 or 90-day terms. It gives you a clearer view of the company behind the order, so you can make a more informed decision about whether to offer credit, reduce the limit or ask for payment upfront.
Why check before offering payment terms?
Payment terms are a form of trust. They should be based on more than a promising sales conversation, a professional website or a strong first order.
A company credit check can help you understand whether a customer appears financially stable, how they manage payment obligations and whether there are warning signs that need further review.
This is especially useful when:
- a new customer asks to pay by invoice
- an existing customer wants a higher credit limit
- an order is larger than usual
- a customer requests longer payment terms
- payment behaviour has started to change
- your business would be exposed if the invoice was delayed
How to run a business credit check
1. Confirm the company identity
Start by checking that you are reviewing the right business. Confirm the registered company name, company number, trading address and director details where available.
This matters because trading names, group structures and similar business names can create confusion. Accurate identification helps make sure your decision is based on the right company profile.
2. Review the business credit score
The credit score gives you a quick indication of potential credit risk. It can help you decide whether the company appears suitable for the level of credit being requested.
Use the score as a starting point, not the full decision. A low or weakening score may suggest you need to look more closely before offering terms.
3. Check payment behaviour
Payment behaviour can show how reliably a business pays its obligations. If there are signs of late, inconsistent or worsening payments, consider whether standard terms are appropriate.
For SMEs, this is one of the most practical indicators because another company’s payment habits can directly affect your cash flow.
4. Look for CCJs and insolvency indicators
County Court Judgments can indicate unresolved debt issues. Insolvency-related indicators may suggest more serious financial pressure.
One historic issue may need context. Recent, repeated or unresolved issues should prompt a more cautious approach.
5. Review filings and company details
Public filings, company status and director information can help you assess whether the business appears active, transparent and properly maintained.
Late filings, unusual changes or incomplete information should not be ignored, especially where the order value is high.
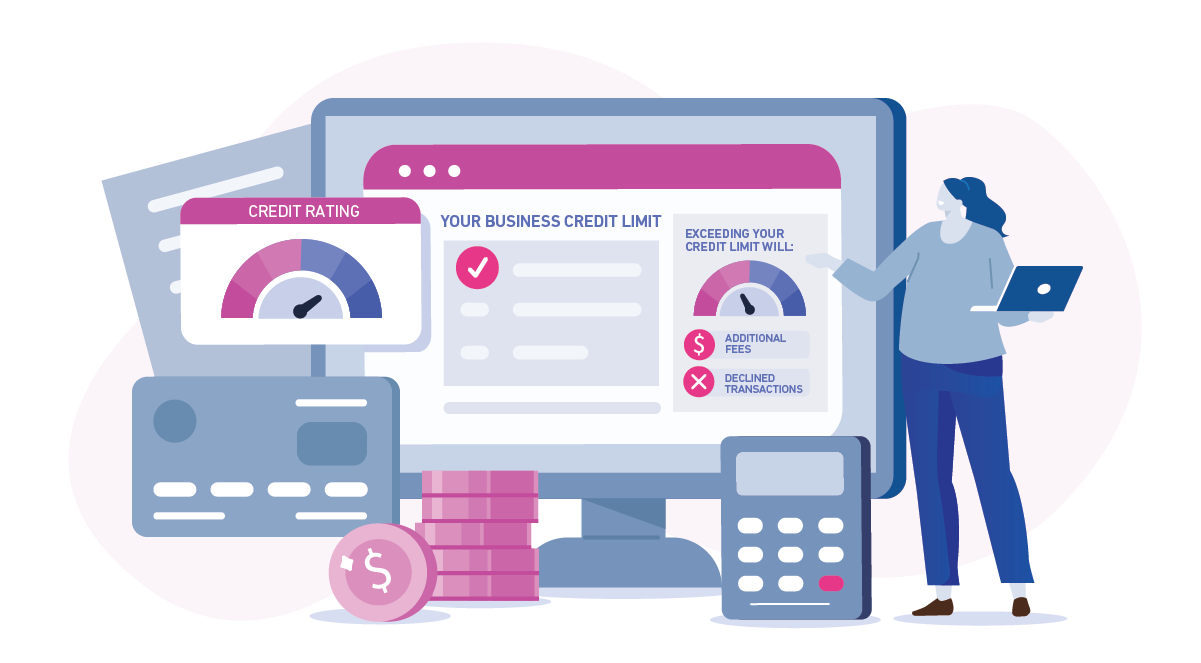
Turn the check into a payment terms decision
The purpose of a business credit check is to support action. Once you have reviewed the company’s credit profile, you can decide whether to:
- offer standard payment terms
- set a lower credit limit
- shorten the payment window
- request a deposit or partial upfront payment
- ask for payment in full before delivery
- monitor the customer before increasing exposure
- decline credit terms for now
This helps make credit decisions more consistent and reduces reliance on instinct alone.
Check your own business credit profile too
Customers, suppliers and lenders may also check your business before agreeing terms, finance or partnerships. Reviewing your own business credit profile helps you see what other businesses may be using to assess you.
The takeaway
Offering payment terms can support growth, but it should be backed by clear checks. A business credit check gives you a more informed view of customer risk before money is on the line, helping you protect cash flow and make stronger credit decisions.
Before you offer payment terms
Review the company’s credit profile before you agree to invoice later. A company credit check can help you assess credit risk, payment behaviour, CCJs, filings and other indicators before you extend credit.
Make credit decisions with more confidence
Use company credit insight to choose terms that match the level of risk and exposure your business is comfortable taking on.
Check a business before offering payment terms